How Much Should a Small Business Set Aside for Taxes?
The percentage most owners use is 25 to 30 percent of profit, and it is a budgeting habit rather than an IRS rule. This guide explains what sits inside that number, the quarterly deadlines the IRS sets, and the simple system that stops tax bills from ambushing your cash flow.
Every spring, the same story repeats in small businesses everywhere. The year went well. The bank balance looked healthy, and then the tax bill arrived and ate money that was already meant for stock, equipment or wages.
Nobody set out to underpay. They just never kept the tax money apart from the working money, so a number that was never theirs felt like theirs all year.
This guide gives you the percentage to work with and shows where that number comes from. Then it shows you the IRS rules under it, because those rules decide whether you get a penalty.
It ends with a simple weekly and quarterly system that keeps the money apart, and you do not need a finance degree to run it.
Key Takeaway: Set aside 25 to 30 percent of profit, not revenue, and keep it in a separate account. The figure is a budgeting habit, not an IRS rule. It works because it quietly covers both taxes a self-employed owner pays: income tax and self-employment tax.
The percentage to start with: 25 to 30 percent of profit
Here is the figure most accountants and small business advisors suggest as a starting point: set aside 25 to 30 percent of your net profit for federal taxes. Read that sentence carefully, because two parts of it do heavy work.
First, it is a percentage of profit, not of revenue. Profit means what is left after business expenses. A business that takes in $8,000 in a month and spends $5,000 running itself has $3,000 of profit, and the set-aside applies to the $3,000.
A budgeting rule of thumb, not an IRS rule
Second, and this matters, the 25 to 30 percent figure is a budgeting rule of thumb. It is not an IRS rule, a tax rate, or anything the IRS publishes.
It is a planning habit, and it lands close to what many sole proprietors and single-member LLC owners owe once their income tax and self-employment tax are added together.
Your real bill depends on your profit level, your business structure, your deductions, your state, and what else you earn. Treat 25 to 30 percent as the amount you park in a separate account so the real bill, whatever it turns out to be, never lands as a shock.
If your income is low, the lower end will probably cover you. If profits are strong, or you live in a state with its own income tax, plan toward the top end or beyond. The rest of this guide shows why the range works and where it can break.
What the IRS actually requires: pay as you go
The US tax system is pay as you go. Employees never notice this because their employers withhold tax from every paycheck. A business owner has no employer to do that job, so the IRS expects you to do it yourself through estimated tax payments, usually four times a year.
The IRS guidance on estimated taxes says you generally have to make estimated payments. You need them if you expect to owe tax of $1,000 or more when your return is filed.
This applies to individuals, including sole proprietors, partners and S corporation shareholders. You work out the amount on Form 1040-ES, and you can pay online through IRS Direct Pay or the EFTPS system.
The four due dates for a calendar-year business are not evenly spaced, which catches people out:
| Payment | Income period it covers | Due date |
|---|---|---|
| 1st | January 1 to March 31 | April 15 |
| 2nd | April 1 to May 31 | June 15 |
| 3rd | June 1 to August 31 | September 15 |
| 4th | September 1 to December 31 | January 15 of the next year |
If a due date falls on a weekend or a federal holiday, it moves to the next business day. Put all four dates in your calendar on day one, not the week before the first one arrives.
The two taxes hiding inside your percentage
Owners who save too little usually forget that a self-employed person pays two layers of federal tax on the same profit.
The first layer is ordinary income tax, charged at your normal rates on your taxable profit. The second layer is self-employment tax, which covers Social Security and Medicare. The IRS charges it at 15.3 percent, and it applies to 92.35 percent of your net self-employment earnings, not the full amount.
It is the price of being your own employer. An employee’s employer quietly pays half of this tax, while a business owner pays both halves. There is one small comfort.
The IRS self-employed individuals tax center notes that you can deduct the employer-equivalent half of the self-employment tax. You take that deduction when you work out your income tax.
That 15.3 percent layer is exactly why the 25 to 30 percent set-aside exists. Income tax alone might point to a smaller figure, but add self-employment tax and the total lands in the range the rule of thumb describes.
Featured Insight: On $60,000 of profit, self-employment tax alone comes to roughly $8,478, before a cent of income tax is added. That single layer is why a set-aside in the mid-teens leaves owners short every spring.
A worked example on $60,000 of profit
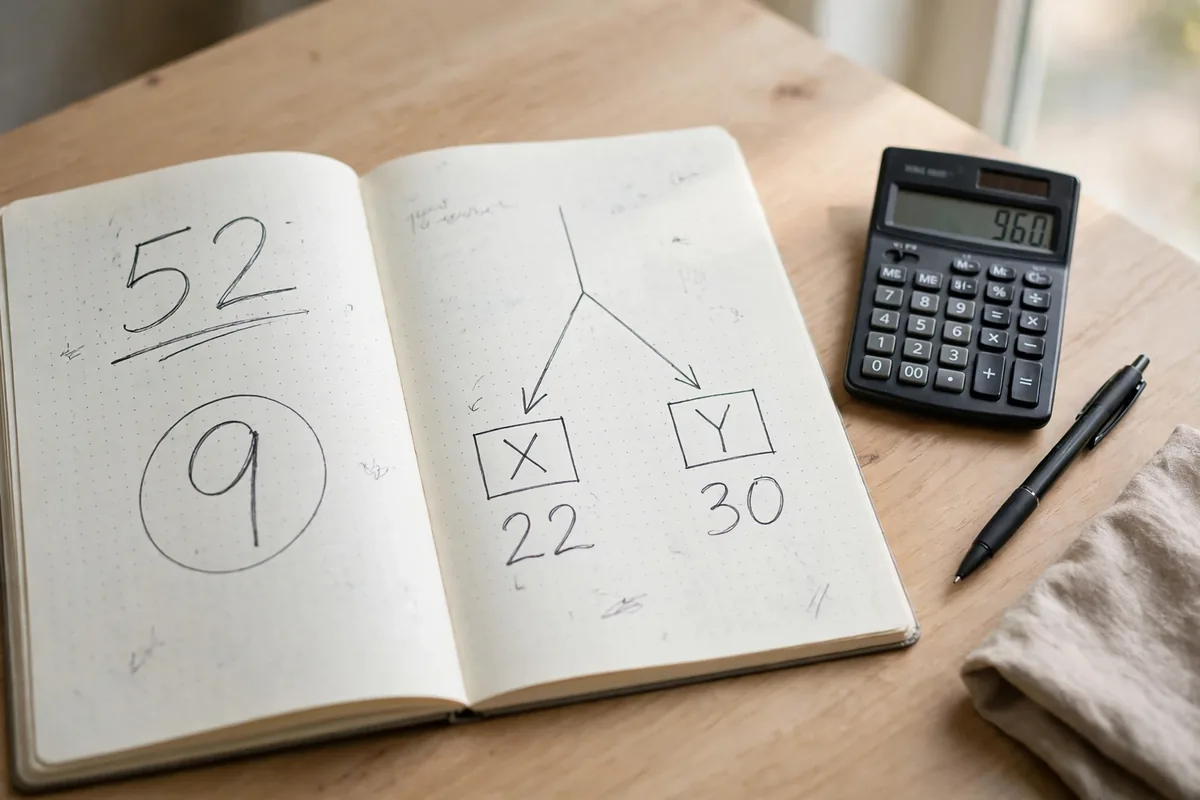
Numbers make this clearer. Imagine a sole proprietor finishes the year with $60,000 of net profit. The figures below just show the idea, not a real tax calculation, because real returns include deductions and credits that this example leaves out.
The set-aside habit says to park 25 to 30 percent of profit: $15,000 to $18,000 across the year. Now look at the self-employment tax on its own.
Take $60,000, multiply by 92.35 percent to get $55,410, then apply 15.3 percent. The self-employment tax comes to roughly $8,478.
Income tax comes on top of that, based on the profit after adjustments, like the deduction for half of the self-employment tax. Add the two together and you can see why a set-aside in the mid-to-high teens would leave this owner short.
And you can see why 25 to 30 percent gives a good cushion for federal tax in a normal year.
If your profit were $25,000 instead, the same habit would save a bit too much, because your income tax layer would be thinner. Over-saving is the good problem: the extra simply becomes next year’s cushion, or it comes back to the business after you file.
The safe harbor: how owners stop guessing
Estimated payments raise an obvious question. How can you pay tax during the year on a profit you will not know until the year ends? The IRS answer is a set of safe harbor rules, and they are the most useful thing in this guide.
In general, you avoid an underpayment penalty if you pay in enough tax during the year, through withholding and estimated payments combined. The amount has to reach at least the smaller of two figures.
The first is 90 percent of the tax you end up owing for the current year. The second is 100 percent of the total tax shown on last year’s return.
If last year’s adjusted gross income was over $150,000, or $75,000 if you file as married filing separately, that second figure rises to 110 percent of last year’s tax.
The real magic sits in the prior-year option. Last year’s tax is a known number, printed on a return you already filed. Take that number, divide it by four, and pay that amount each quarter, and you are safe from underpayment penalties even if this year turns out far better than last year.
You may still owe a balance when you file, but you will owe it with no penalty attached. New businesses have no prior-year return, so they lean on the percentage habit instead and review it after the first filing.
What happens if you pay too little, or pay late
The IRS does not treat an honest shortfall like fraud, but it does charge for it. If your payments fall short of the safe harbor levels, an underpayment penalty applies to the amount you underpaid for the period it stayed unpaid.
The penalty works like interest. The IRS works it out on Form 2210, using a rate it sets each quarter. So the cost grows the longer a shortfall sits there.
Two habits keep you out of this trouble. The first is the safe harbor itself. Pay in at least 100 percent of last year’s tax, and the penalty cannot touch you, however good the current year turns out. If the higher-income limit applies, the figure is 110 percent.
The second is rhythm. Paying a sensible amount every quarter beats one huge payment in January. The IRS looks at each payment period on its own, and a late catch-up does not fully wipe out an early gap.
The system that makes it automatic
Percentages fail when they depend on willpower. Systems do not. Here is the setup that works for most one-person and small-team businesses.
Open a separate savings account used for nothing except tax. Move your set-aside percentage into it on a fixed rhythm: every time a client pays you, every Friday, or at month end when you look at the books. The rhythm matters less than keeping the money apart.
Money sitting in the operating account will be spent by the business, because the business always has a plausible use for it. Money in the tax account gets left alone, because its job is obvious.
Each quarter, pay the IRS from that account by the due dates above. After you file your yearly return and know the real bill, move any leftover into the business, or leave it as a head start on next year.
Your income may be seasonal. Many product businesses face this, and the clothing brand guide on this site covers the same pattern. In a strong quarter, you move a bigger amount that month. You do not copy a fixed amount from a quiet month. Your percentage stays the same while the dollars follow your profit.
Two other pots of money that are not yours
Sales tax is the trap that catches retailers and online sellers. When you collect sales tax from a customer, that money belongs to the state from the moment it lands.
It passes through your account, but it is never revenue, and it should never be counted in your profit or spent on stock. Hold it apart and send it in on the schedule your state sets.
State income tax is the second pot. Most states with an income tax expect their own estimated payments. They use their own forms, and their dates sometimes differ from the federal ones.
This is one more reason the set-aside is a range, not one fixed number: an owner in a state with no income tax should not park the same percentage as an owner in a high-tax state.
The owners who never fear April are not the ones who earn the most. They are the ones who moved the tax money out of reach every single week.
When to stop doing this yourself
A percentage habit and a calendar will carry a simple business a long way.
Bring in a tax professional when any of these become true. You hire employees and start running payroll. You choose S corporation tax status and must set a salary for yourself.
Your profit grows so much that the gap between 25 and 30 percent is real money. Or you sell into many states and your sales tax duties grow.
An hour of professional advice at that point is not a luxury. It is cheaper than the penalties it prevents.
It also helps to write your tax percentage into the plan for the business itself, next to your prices and your costs. The financial section of a one-page business plan is a good home for it. A target you can see is a target you fund.
Questions owners ask about setting money aside for tax
Is the 25 to 30 percent figure an official IRS rate?
No. It is a budgeting rule of thumb used by advisors and accountants to help owners save enough during the year. The IRS never publishes a single set-aside percentage, because your real tax depends on your profit, structure, deductions and state.
What the IRS does publish are the estimated payment rules, the due dates and the safe harbors described above.
What if my business makes no profit this year?
Income tax and self-employment tax are charged on profit. So a year with no net profit generally means no federal income tax bill from the business. Keep good records anyway. The loss itself belongs on your return and can matter for other years. And keep making transfers in any month you do turn a profit.
What if my income arrives unevenly, in a few big months?
The IRS allows for this. It is called the annualized income installment method, and you work it out on Form 2210. It lets your payments follow the months when the money actually arrived.
It takes more record keeping, but it beats paying early quarters on income you had not earned yet. The percentage habit still applies. Move your set-aside in the month each payment lands.
Does an LLC change how much I should set aside?
A single-member LLC is usually taxed like a sole proprietorship. So the same percentage habit applies. A multi-member LLC is taxed like a partnership. Each member handles estimated taxes on their share.
An LLC or corporation that chooses S corporation tax status changes the picture. The owner takes a salary through payroll, with tax withheld, plus distributions. That is a point where professional advice pays for itself.
Do these rules apply in my first year of business?
Yes. The estimated payment rules apply from the first year you expect to owe $1,000 or more.
The one soft landing is narrow. It applies only if three things are true. You had no tax liability at all for the previous year. You were a US citizen or resident for that whole year. And that tax year covered twelve months.
If all three hold, the IRS does not require estimated payments for the year that follows.
Most new owners with any prior income do not qualify. So plan as if the rules apply to you from your first month of profit.
I also have a job with a paycheck. Does that change anything?
Yes, and it can help you. Tax withheld from wages counts toward the same safe harbor totals as estimated payments. Some owners in this position raise the withholding on their paycheck instead of making separate quarterly payments. Your set-aside percentage then applies only to the gap your withholding does not cover.
James Walker writes about business, marketing and finance for USA, UK, Canada and Australia. Contact: contact@businessturnpoint.com